
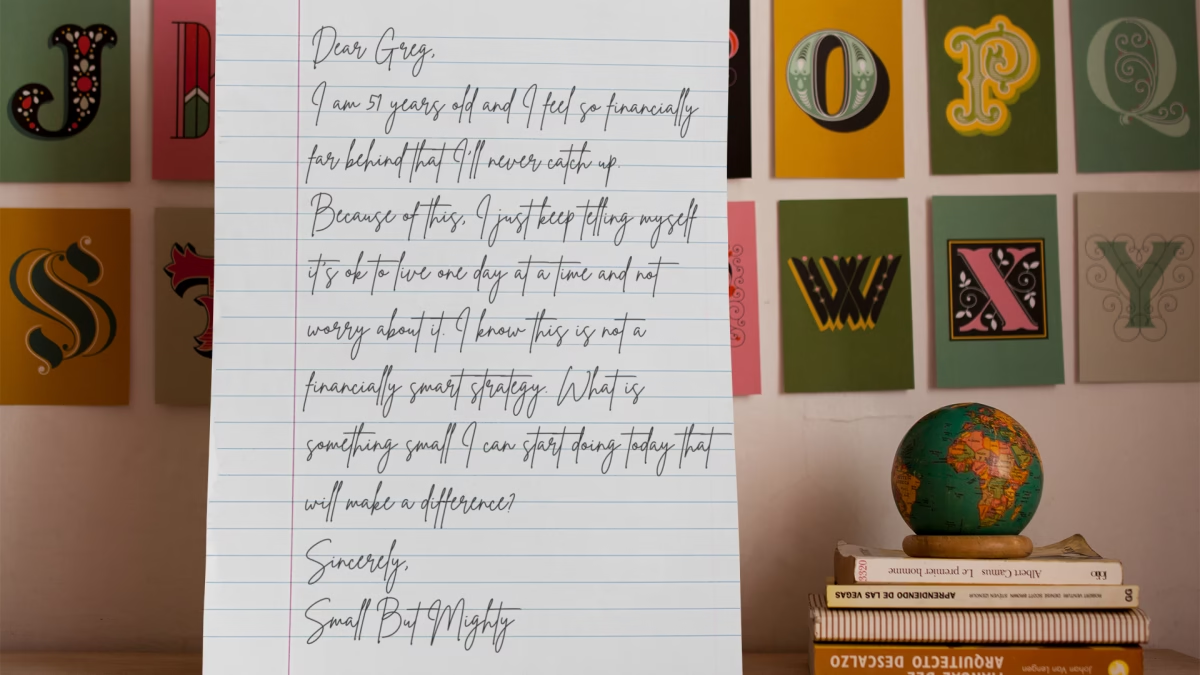
Hi everyone! Welcome to the first official installment of my Financial Sobriety column. I’m Greg, a former financial advisor, author of the forthcoming book 12 Steps to Financial Sobriety, and leader of The Sober Money Club financial support group. I’m so glad you’re here.
This first question might hit close to home for anyone who feels like it’s too late to take control of their finances.
Let’s dig in…
Dear Greg,
I am 51 years old and I feel so financially far behind that I’ll never catch up. Because of this, I just keep telling myself it’s ok to live one day at a time and not worry about it. I know this is not a financially smart strategy. What is something small I can start doing today that will make a difference?
Sincerely,
Small But Mighty
Hey Small But Mighty!
First, thank you. This question took guts to write.
Second, let’s talk about “one day at a time.” In the rooms, that phrase means “do today’s work.” Go to a meeting. Call your sponsor. Don’t drink for the next 24 hours.
With money, that phrase can become “I’ll deal with it later.” And that’s where the danger happens. Later becomes never and the balance keeps sitting there in dark.
That’s the opposite of financial sobriety.
The word doing damage
Being 51 years old isn’t a problem. Feeling “behind” is. Behind implies a race and a leaderboard. We see everyone else’s glamorous lifestyle on social media, assume they have it all figured and are way ahead. The odds say they are not. In fact, a recent survey shows that over 60% of Americans are living paycheck to paycheck.
There is no leaderboard.
There’s just you and your relationship with money.
The ostrich effect
You’re already aware that not worrying about it is not a financially smart strategy. And that avoidance is what human beings do when we think we’re at the bottom of that nonexistent leaderboard.
Behavioral economists have a name for it. They call it the “ostrich effect.” It means we look less often when we suspect the news is bad. Researchers found people who rarely check their balances spend far more erratically, especially right after payday. They’re flying blind.
Your one small thing
Take 90 seconds and open your bank app. Look at the number and write it down. Then close the app.
That’s it.
Now do that every day. Add it to the morning routine. Coffee, breakfast, bank app.
You’re not fixing anything. You’re just going to the meeting.
It feels pointless. But think about what you’d tell a newcomer to the rooms when they tell you “Meetings are pointless. I’m just sitting there.” You’d tell them, “keep coming back.” That’s what I want you to start doing with your balance.
Awareness comes before action. You do Step 1 before Step 7. You don’t need a whole new budget right now.
Do this for a few weeks and here’s what you’ll notice: nothing major. That number you’ve been avoiding stops having the same emotional impact it did on day one. It becomes “just a number.” And that’s the point.
What you’re really asking
You asked about one small thing, but I think you were really asking whether it’s too late to bother.
It’s not.
Even the government thinks so. In fact, the IRS lets people 50 and over put an extra $8,000 into their 401(k) on top of the standard limit. It’s called a catch-up contribution. When the tax code says you have time, you know you’re not alone.
You already know how to do hard things one day at a time. Now it’s time to do it one dollar at a time.
Until next time,
Greg
Financial disclaimer: This column provides general financial education and reflects the author’s perspective. It is not individualized financial, investment, tax or legal advice. Consider consulting a qualified professional about your specific circumstances.
HEALTH & WELLNESS: Financial Sobriety – A New Column About Taking Money One Day at a Time, Too

The Sober Curator’s MENTAL HEALTH + WELLNESS section is your go-to guide for nurturing emotional well-being—especially for those in recovery. Explore resources, expert insights, and personal stories that connect the dots between mental health, sobriety, and self-care. From managing anxiety and depression to building mindfulness and emotional resilience, we provide practical tools and inspiration to help you thrive alcohol-free. By fostering open, stigma-free conversations, we empower our community to make emotional wellness a cornerstone of long-term recovery.
Dedicated columns on this TSC channel:
- Codependency – Insights & Recovery with Sober Curator Contributor Dr. Sarah Michaud
- Financial Sobriety – with Sober Curator Contributor Greg Downs, author of the forthcoming book 12 Steps to Financial Sobriety, and leader of The Sober Money Club financial support group.
- Mastering Mental Fitness with Sober Curator Contributor James Gwinnett
- Mental Health – Emotional Wellness in Recovery
- Relationships – Love, Connection & Boundaries in Sobriety
- Sober Poetry – Recovery in Verse
- Speak Out! Speak Loud! – Stories & Creative Expression in Recovery
- Spiritual Substance – Mindfulness, Science & Soul with Senior Sober Curator Contributor Lane Kennedy
- Wellness As A Way of Life – Sustainable Health for Powerful Women with Senior Sober Curator Contributor Megan Swan

Recovery is hard 24/7, 365 – Please know that resources are available
If you or someone you know is experiencing difficulties surrounding alcoholism, addiction, or mental illness, please reach out and ask for help. People everywhere can and want to help; you just have to know where to look. And continue to look until you find what works for you. Click here for a list of regional and national resources. If your life or someone else’s is in imminent danger, please call 911. If you are in crisis and need immediate help, please call: 988.
Follow The Sober Curator on X, the artist formerly known as Twitter
Is 51 too late to take control of your finances?
No. Although starting earlier provides more time for savings to grow, steps taken at 51 can still improve your financial stability and retirement outlook. Your best strategy will depend on your income, expenses, debts, savings and access to retirement plans.
What is financial sobriety?
In Greg’s column, financial sobriety means developing an honest, intentional and accountable relationship with money. It begins with awareness rather than avoidance and focuses on making manageable decisions consistently.
What is one small step for someone avoiding their finances?
Start by looking at your available bank balance without immediately judging yourself or attempting to solve everything. Regularly reviewing your accounts can help replace uncertainty with accurate information. If checking your balance causes overwhelming anxiety, consider seeking support from a qualified financial counselor.
What is a 401(k) catch-up contribution?
A catch-up contribution allows eligible participants age 50 and older to contribute more than the standard annual limit to certain workplace retirement plans. Limits can change annually, so check the IRS retirement plan contribution limits and your employer’s plan rules.